August 2026 | NYREDeals™
A NYC multifamily listing might say:
$5.5 million asking price.
7% cap rate.
Strong income.
Upside potential.
That sounds good.
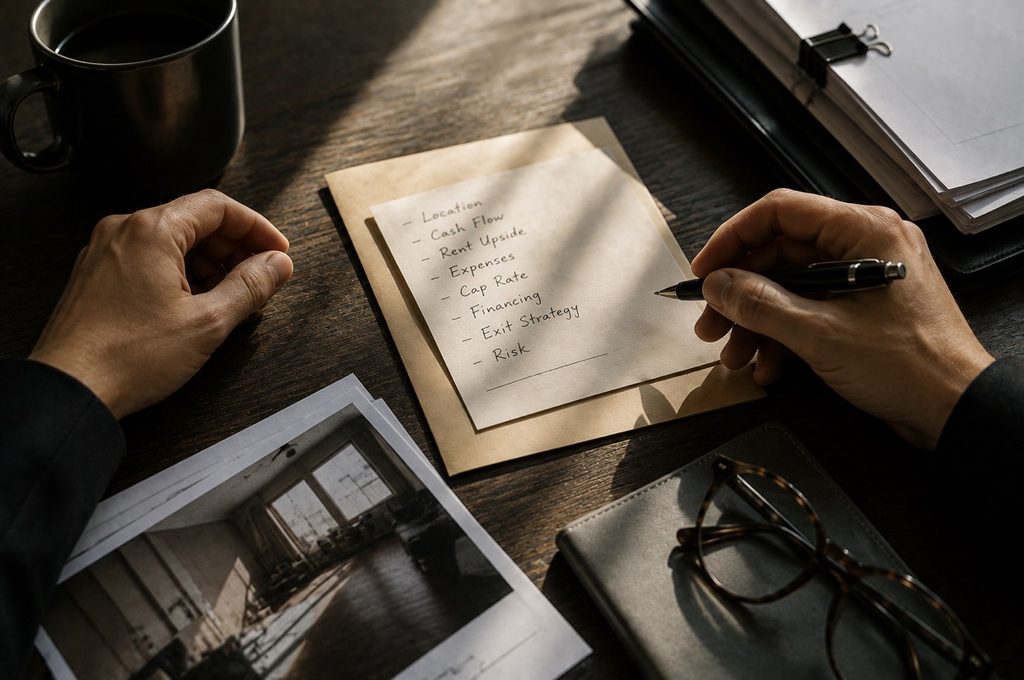
But a seasoned investor doesn’t make an offer based on the headline numbers.
They start asking:
Is the income real?
Are the expenses complete?
What will the lender recognize?
What needs to be repaired?
And what am I actually earning after debt?
Because the number advertised on the listing and the number an investor ultimately underwrites can be very different.
Start With the Rent Roll—but Don’t Stop There
The rent roll tells you what each unit is supposed to be paying.
That’s the starting point.
But seasoned investors want to know what is actually being collected.
A building may show annual scheduled rent of $900,000, but if tenants are consistently behind and actual collections are $840,000, underwriting the full $900,000 creates a return that doesn’t really exist.
That’s why investors compare the rent roll against historical operating statements, bank deposits and collection history.
Fannie Mae’s multifamily underwriting standards similarly begin with actual in-place rents for occupied units and require analysis of vacancy and operating income—not simply the seller’s projected rent. [1]
Scheduled income is not the same thing as collected income.
Then Build the Real NOI
Net Operating Income—or NOI—is one of the most important numbers in an income-producing property.
At its simplest:
Income – Operating Expenses = NOI
Fannie Mae defines NOI as a property’s effective gross income minus operating expenses. [2]
Suppose a building collects:
$900,000 in annual income
and costs:
$500,000 per year to operate
The NOI is:
$400,000
That’s the income generated by the property before mortgage payments and certain other costs.
But the calculation is only useful if the expenses are realistic.
That means reviewing the actual bills behind:
Property taxes
Insurance
Utilities
Repairs and maintenance
Payroll
Management
Legal/accounting
Pest control
Cleaning
Other recurring operating costs
A seller can make a building look more profitable simply by presenting unusually low or incomplete expenses.
Experienced buyers normalize them.
Don’t Take the Cap Rate at Face Value
Once you have a believable NOI, the cap rate starts to mean something.
Cap Rate = NOI ÷ Purchase Price
If a property produces $400,000 in NOI and costs $5 million, the cap rate is:
8%
But suppose the listing advertises an 8% cap using $400,000 of NOI—and after reviewing expenses you determine normalized NOI is really $350,000.
At the same $5 million price:
$350,000 ÷ $5,000,000 = 7%
The building didn’t change.
Your understanding of the building did.
That’s why sophisticated investors don’t simply ask:
“What’s the cap rate?”
They ask:
“Whose NOI is that cap rate based on?”
NYC Property Taxes Deserve Their Own Review
Property taxes can materially affect NOI, and NYC’s tax system isn’t something an investor should estimate casually.
Most apartment buildings with more than three units generally fall into Tax Class 2. NYC’s Class 2 property-tax rate for tax year 2026 is 12.439% of taxable assessed value, not 12.439% of the property’s purchase price. [3]
That distinction matters.
Investors should review:
Current assessed value
Taxable assessed value
Exemptions or abatements
Tax-class status
Assessment history
Potential future changes
And don’t automatically assume today’s tax bill will remain today’s tax bill forever.
NYC reported that the total assessed value of Class 2 rental apartments increased 6.8% on the FY2027 tentative assessment roll. [4]
A property with thin margins can feel very different when taxes rise.
Insurance Can Change the Deal Too
A seller’s historical insurance expense may not be what a new buyer will pay.
That’s why seasoned investors often obtain an insurance indication or quote before becoming too comfortable with the NOI.
If the seller paid $45,000 last year but your actual quote is $80,000, that’s another $35,000 coming directly out of NOI.
At a 6% cap rate, a $35,000 NOI difference represents roughly $583,000 of value:
$35,000 ÷ 6% ≈ $583,000
That’s why seemingly small operating-expense mistakes can create large valuation differences.
Then Ask: Can the Property Support the Debt?
Cap rate tells you about the property before financing.
But most investors use debt.
That’s where DSCR—Debt Service Coverage Ratio—comes in.
DSCR compares the property’s underwritten cash flow with its annual mortgage payments.
Fannie Mae defines underwritten DSCR as the ratio of underwritten net cash flow to annual debt service. [5]
A simplified example:
NOI / qualifying cash flow: $400,000
Annual mortgage payments: $320,000
DSCR = 1.25x
That means the property generates $1.25 of qualifying cash flow for every $1.00 of debt service.
If DSCR drops close to 1.00x, there isn’t much cushion.
Below 1.00x, the property’s income isn’t covering the debt service under that calculation.
And here’s something investors sometimes learn late:
The lender may underwrite the property more conservatively than the buyer does.
The buyer’s NOI might not be the lender’s NOI.
Leverage Can Improve Returns—and Increase Risk
Investors also look closely at loan-to-value, or LTV.
If you’re buying a $5 million building and borrowing $3.5 million:
LTV = 70%
Higher leverage means the investor contributes less equity.
That can increase the return on the investor’s cash when the investment performs well.
But it also means:
More debt service
Less room for income declines
Greater refinancing exposure
More sensitivity to interest rates
Seasoned investors aren’t necessarily trying to borrow the maximum amount available.
They’re asking:
How much debt can this property safely carry?
That is a different question.
What Happens After You Buy It?
A property can have attractive current NOI and still require a large check immediately after closing.
That’s why investors look at CapEx—capital expenditures.
A building may soon need:
A roof
Boiler
Elevator work
Façade repairs
Plumbing or electrical upgrades
Windows
Local Law compliance work
Apartment renovations
Suppose you buy a building for $5 million but know you’ll need to spend another $750,000 during the first two years.
Your economic basis isn’t really just $5 million anymore.
It’s moving toward $5.75 million, before considering acquisition and financing costs.
A cheap building with significant deferred maintenance can become expensive very quickly.
In NYC, Regulatory Due Diligence Can Change the Income
This is particularly important with rent-regulated buildings.
Owners of rent-stabilized units are required to register those apartments annually with New York State’s Division of Housing and Community Renewal. [6]
An investor should understand whether the rent roll is supported by the property’s regulatory history.
That can include reviewing:
DHCR registrations
Preferential rents
Legal regulated rents
Apartment status
Regulatory agreements
Applicable tax-benefit programs
You don’t want to underwrite income you later discover cannot legally be collected.
The same goes for physical violations.
NYC’s HPD Online allows investors to review open housing violations and orders, including violations categorized as hazardous or immediately hazardous. [7]
A building’s problems don’t disappear because ownership changes.
Seasoned Investors Also Underwrite the Downside
This is where underwriting becomes more than verifying the seller’s numbers.
Ask what happens if:
Vacancy increases.
Insurance rises again.
Taxes increase.
A major repair occurs.
Interest rates remain elevated when the loan matures.
Rent growth is weaker than expected.
If a deal only works when every assumption goes right, there’s very little margin for error.
A strong investment doesn’t necessarily need pessimistic assumptions.
But it should survive reasonable ones.
Price Per Unit and Price Per Square Foot Still Matter
Cap rate isn’t the only valuation tool.
NYC investors commonly compare:
Price per unit
Price per square foot
Cap rate
Comparable sales
Each tells you something different.
A building may look cheap at $150,000 per unit but expensive on a cap-rate basis because the rents are low.
Another building may look expensive per unit but produce exceptional NOI.
That’s why seasoned investors don’t allow one metric to make the decision.
They triangulate value.
If the cap rate, price per unit, price per square foot and comparable sales are all telling very different stories, find out why.
Then Look at the Exit
Investors sometimes spend so much time figuring out how to buy a property that they forget to think about how they’ll eventually get out.
Before making an offer, ask:
Who is likely to buy this from me later?
If the business plan requires selling in five years, what will make the next investor want it?
Will NOI be higher?
Will the building be in better physical condition?
Will units have been renovated?
Will the debt environment matter?
And most importantly:
What exit cap rate am I assuming?
If you buy at a 6% cap but your entire projected return assumes you’ll sell later at a 4.5% cap, you’re depending heavily on the market becoming more favorable.
Seasoned investors tend to be careful about underwriting appreciation they don’t control.
What Does the Deal Look Like After All of That?
Go back to the original listing:
$5.5 million asking price
7% advertised cap
Strong income
Value-add potential
After underwriting, you may discover:
Collections are lower than scheduled rents.
Insurance is understated.
Taxes may increase.
$500,000 of capital work is needed.
The lender’s NOI is lower than the seller’s NOI.
Suddenly, the price you’re willing to pay may not be $5.5 million anymore.
And that’s the point.
Experienced investors aren’t trying to prove that the listing is wrong.
They’re trying to determine:
At what price does the deal make sense for me?
The Numbers That Matter Most
Before making an offer, a serious investor should understand at minimum:
What the property actually collects.
What it actually costs to operate.
The sustainable NOI.
The cap rate based on that NOI.
How much debt the property can comfortably support.
The property’s regulatory and physical risks.
The capital required after closing.
The basis compared with competing properties and recent sales.
And what has to happen for the investment to succeed.
Because a property’s asking price tells you what the seller wants.
The underwriting tells you what the property is worth to you.
And those two numbers don’t always have to agree.
⸻
NYREDeals™
New York Real Estate Deals
NYREDeals™ connects investors with on-market and off-market investment opportunities across New York City.
Follow NYREDeals™ for NYC investment opportunities, market intelligence and investor education.
Information current as of August 2026. This article is for informational purposes only and does not constitute investment, legal, tax or financial advice.
References
[1] Fannie Mae Multifamily Guide — Income Analysis. Underwriting guidance for actual rents, vacancy and effective gross income. (mfguide)
[2] Fannie Mae Multifamily Selling and Servicing Guide — Net Operating Income / Property Income and Underwriting. NOI and operating-expense methodology. (mfguide)
[3] NYC Department of Finance — Property Tax Rates. Tax Year 2026 Class 2 rate: 12.439%. (New York City Government)
[4] NYC Department of Finance — FY2027 Tentative Assessment Roll. Class 2 rental-apartment assessed value increased 6.8%. (New York City Government)
[5] Fannie Mae Multifamily Guide — Debt Service Coverage Ratio / Underwritten DSCR. (mfguide)
[6] New York State Homes and Community Renewal — Rent Registration. Rent-stabilized apartments must be registered annually with DHCR. (Homes and Community Renewal)
[7] NYC Department of Housing Preservation and Development — HPD Online / Violations.Property records include complaints, violations, orders and other building information. (New York City Government)
NYC Real Estate News